Fruit Wine Distribution Opportunities in the Chinese Market
Discover strategic fruit wine distribution opportunities in the Chinese market. Learn how category producers can navigate emerging demographics, retail channels, and regulatory entry.
China’s beverage alcohol sector is experiencing a structural realignment. While standard imported grape wines navigate a recalibration—with China importing approximately $1.6 billion in wine and related products in 2024 according to data from the General Administration of Customs China (GACC)—non-grape fruit wines are carving out a high-growth category of their own. Driven by consumer appetite for low-alcohol alternatives, approachable flavor profiles, and artisanal branding, international and domestic producers face a unique window of commercial opportunity.
According to an industry assessment by Future Market Insights (2026), the global fruit wine market is projected to expand at a 10.4% compound annual growth rate (CAGR) between 2026 and 2036, reaching $3.03 billion. Crucially, the Chinese market is forecast to grow at an individual CAGR of 7.5% over the same period, outperforming many mature Western beverage markets. Capturing this demand requires international wineries, commercial cideries, and craft distillers to understand consumer motivations, structure distribution routes effectively, navigate regulatory compliance, and engage with verified local buyers.
Shifting Demographics: Who Drinks Fruit Wine in China?
Traditional alcoholic beverage consumption in China has long been centered around business banquet culture dominated by high-proof baijiu and full-bodied red grape wines. However, generational shifts and changing lifestyles have unlocked a parallel beverage market.
The Rise of Gen Z and Female Consumers
Younger urban professionals, particularly Gen Z and female demographics, are driving the adoption of lower-alcohol, sweet, and fruit-forward profiles. Heavy tannins and high astringency found in conventional grape wines often present a barrier to occasional drinkers. In contrast, fruit wines—ranging from plum (ume), lychee, peach, and mulberry to blackberry, apple, and passion fruit—offer balanced acidity and distinct natural aromas. These products align closely with China's "guochao" (cultural pride) and "self-pleasing" (yueji) lifestyle trends, where casual social drinking with friends (xiaozhuo) or solo unwinding at home replaces formal banquet dining.
Overcoming Market Homogenization with Premiumization
Historically, the domestic Chinese fruit wine segment was plagued by OEM manufacturing and product homogenization. Early reporting by ChemLinked FMCG highlighted that over 90% of early local fruit wine lines were OEM-produced, resulting in taste fatigue and inconsistent quality. This dynamic creates an advantage for foreign producers and high-end craft brands. Chinese consumers actively seek authentic provenance, natural fermentation methods, zero artificial additives, and refined packaging design. Positioning your product as an artisanal, origin-certified fruit wine provides an immediate point of differentiation against mass-market domestic blends.
Multi-Channel Distribution Routes: Online to Offline
To build a scalable commercial footprint in China, producers cannot rely solely on conventional alcohol distributors. A modernized, hybrid route-to-market strategy is essential.
Digital Channels and Social Commerce
Unlike Western markets where physical retail dominates initial brand discovery, brand acceleration in China often originates online. Platforms such as Douyin (TikTok), Xiaohongshu (RED), and Tmall enable digital-first alcohol brands to test consumer response rapidly. The USDA Foreign Agricultural Service noted in its 2025 Wine Market Update that localized digital storytelling and Key Opinion Leader (KOL) engagement on platforms like Red Note and Douyin are critical for brands looking to appeal to lifestyle-oriented Chinese demographics. Live-streaming sales and creator endorsements generate immediate trial purchases, creating consumer pull that strengthens negotiations with regional tier-1 and tier-2 offline distributors.
Offline Retail and Modern Trade
While e-commerce establishes brand identity, off-premise retail volume remains vital for volume stability. The global analysis by Future Market Insights (2026) projects supermarkets and hypermarkets to dominate the global fruit wine distribution landscape with a 41.8% value share. In China, membership warehouse clubs like Sam’s Club and Costco, alongside boutique supermarkets like Ole’ and Hema Fresh, are aggressively expanding their private procurement of imported alternative beverages. Securing placement in these venues requires distributors with established cold-chain capabilities, compliant shelf-life verification, and consistent replenishment logistics.
On-Premise Dining and Lifestyle Bistros
On-premise consumption is shifting from formal dining tables to informal social spaces. Izakayas, Asian fusion bistros, hot pot venues, and dedicated low-alcohol cocktail lounges are actively seeking fruit wine SKUs to pair with spicy or savory regional cuisines. Fruit wines serve as accessible base ingredients for signature cocktails or as chilled, by-the-glass offerings that yield higher margins for on-premise operators.
Regulatory Compliance and Market Access for Imported Fruit Wine
Entering China's commercial beverage space requires compliance with national food and agricultural import frameworks administered by the General Administration of Customs of China (GACC).
- Manufacturer Registration (Decree 248): Overseas production facilities manufacturing, processing, or storing alcoholic beverages must be registered under the China Import Food Enterprise Registration system before shipping cargo.
- National Standards (GB Standards): Products must conform to China's National Food Safety Standards, including GB 2758 (Fermented Alcoholic Beverages and Their Integrated Alcoholic Beverages) and specific additive limits under GB 2760. Permitted sulfur dioxide levels, synthetic colorants, and preservatives differ strictly from EU or US regulatory thresholds.
- Chinese Back-Label Compliance (Decree 249): Imported bottles must bear a compliant Chinese label printed or adhered directly to the bottle before customs inspection. Labels must accurately state the product category (e.g., fruit wine / 果酒), country of origin, importer/distributor contact details, alcohol by volume (ABV), production date, and comprehensive ingredient list.
Producers must work alongside experienced importers capable of clearing customs audits swiftly to avoid container detentions at major entry ports like Shanghai, Shenzhen, or Guangzhou. To monitor regulatory shifts, review our updated Market Insights.
Accelerating Distribution Through Strategic Trade Shows
Finding reliable, licensed Chinese importers who understand fruit wine positioning is often the primary bottleneck for foreign producers. Unsolicited outreach rarely yields qualified commercial partnerships. The most direct, cost-efficient path to market access is engaging directly with vetted commercial buyers at international trade exhibitions.
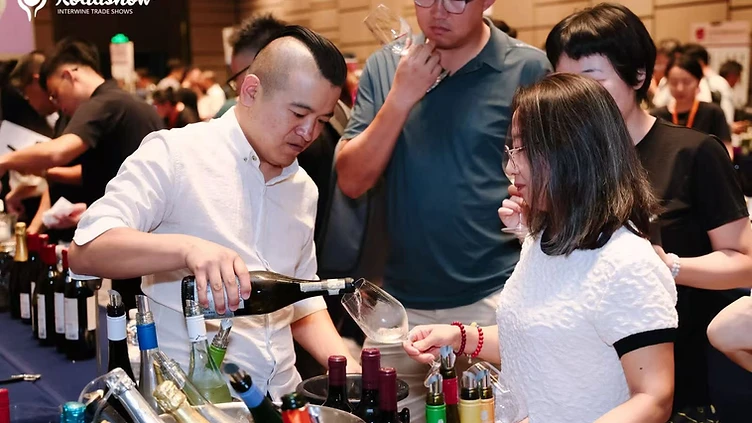
By choosing to Become an Exhibitor at an established platform like INTERWINE, fruit wine brands bypass speculative middlemen and gain direct access to regional distributors, tier-one retail procurement teams, specialized e-commerce aggregators, and hospitality buyers from across Mainland China. Face-to-face tastings allow category buyers to appreciate delicate aromatics, clarify origin provenance, and negotiate commercial distribution contracts tailored for long-term category growth. Discover our curated networking sessions via Business Matching to secure targeted buyer introductions during the show.
Conclusion
China's beverage market is no longer uniform. The intersection of changing consumption habits, a flourishing e-commerce landscape, and consumer willingness to pay for premium, lower-alcohol alternatives creates fertile commercial ground. For global producers possessing quality fruit sourcing and distinctive packaging, expanding your fruit wine distribution opportunities in the Chinese market represents a viable route to high-margin category growth.
Sources
- Future Market Insights: Fruit Wine Market Report (Published May 2026)
- USDA Foreign Agricultural Service: Wine Market Update 2025 - People's Republic of China (Published September 2025)
- ChemLinked REACH24H: China's Fruit Wine Market Analysis (Published June 2020)
Key Takeaways
- —The global fruit wine market is forecast by Future Market Insights to reach $3.03 billion by 2036, with China expanding at a robust 7.5% CAGR.
- —Younger urban demographics, especially Gen Z and female consumers, are driving demand for approachable, low-alcohol beverages suited for casual social settings.
- —High historical levels of OEM homogenization among domestic producers create an opening for authentic, premium imported fruit wines.
- —A successful distribution strategy combines e-commerce and social commerce (Xiaohongshu, Douyin) with offline retail channels like boutique supermarkets and bistros.
- —Market entry requires strict adherence to GACC Decree 248 overseas manufacturer registrations and GB food safety labelling regulations.
Frequently Asked Questions
What is driving the demand for fruit wine in China?
Demand is primarily propelled by Gen Z and female consumers seeking approachable, lower-alcohol alternatives to traditional high-proof baijiu and tannic red wines. The preference for casual social drinking (xiaozhuo), paired with interest in artisanal and fruit-forward profiles, makes the category highly appealing.
What regulatory approvals are needed to import fruit wine into China?
Producers must register their production facility under GACC Decree 248 via the CIFER portal, ensure products meet National Food Safety Standards (GB 2758 and GB 2760 for food additives), and apply compliant Chinese back labels before customs clearance.
Which retail channels perform best for fruit wine distribution in China?
A hybrid model works best. Social commerce platforms like Douyin and Xiaohongshu drive initial consumer awareness, while modern off-premise retail (Sam's Club, Costco, Ole') and casual dining venues (izakayas, fusion bistros) capture consistent volume sales.
How can foreign fruit wine brands stand out against domestic Chinese products?
Because early domestic fruit wines suffered from widespread OEM homogenization, international brands can differentiate themselves by emphasizing pure fruit sourcing, heritage fermentation techniques, clean labels without artificial additives, and distinctive bottle packaging.
How can international fruit wine producers connect with qualified Chinese distributors?
Exhibiting at established trade fairs like INTERWINE provides direct access to vetted wine and spirits distributors, supermarket buyers, and e-commerce aggregators looking for differentiated alcoholic beverage categories.