Understanding China's Wine Distribution Channels
A strategic guide for winery export directors navigating China's evolving multi-tiered wine distribution network, from GACC compliance and Tier-1 hubs to wholesale, retail, on-trade, and digital ecosystems.
For foreign wineries and brand principals, navigating China's wine market requires moving past the outdated single-importer mindset. The mainland Chinese distribution landscape has transformed into an intricate, multi-layered matrix where customs compliance, geographic tiering, digital retail, and specialized on-trade channels converge. Understanding how imported wine moves from container release to the end consumer is the decisive factor between sustained market traction and costly inventory write-offs.
According to the United States Department of Agriculture (USDA) Foreign Agricultural Service Shanghai ATO report published in September 2025, citing General Administration of Customs China (GACC) data, China imported approximately $1.6 billion of wine and related products in 2024, with Australia and France leading suppliers by value. However, commercial success within this multibillion-dollar arena depends directly on choosing the appropriate channel architecture.
The Three-Tier Import Framework: Regulatory Gateways to Wholesale
Unlike direct distribution models common in smaller markets, foreign wineries cannot sell directly to commercial endpoints in China without a licensed legal entity. Every physical shipment must flow through a structured regulatory and commercial sequence before accessing retail or hospitality channels.
[ Overseas Winery / Exporter ]
                 │
                 ▼ (GACC / CIFER Registration & Chinese Labeling)
[ Licensed Chinese Importer ] ───► [ Bonded Warehouse / Customs Clearance ]
                 │
       ┌─────────┴────────┬──────────────────────┐
       ▼                  ▼                      ▼
[ National / Regional   [ Modern Off-Trade     [ Digital / E-Commerce ]
   Wholesalers (T1-T3)]     (Costco, Sam's)       (Tmall, JD, Douyin)
       │
       ├──────────────────┐
       ▼                  ▼
[ On-Trade (HoReCa) ]  [ Specialty Retail / Boutique Bottle Shops ]
1. The Primary Importer and Customs Clearance
All foreign wine manufacturing facilities must secure approval under GACC Decree 248 through the China Import Food Enterprise Registration (CIFER) system prior to dispatch. The domestic partner holding an import-export license executes customs declaration, compliance vetting (GB 15037 wine standards and GB 7718 pre-packaged food labeling), and tax settlement. At the port of entry, importers increasingly leverage temperature-controlled bonded warehouses to defer customs duties, consumption tax, and value-added tax (VAT) until market demand triggers domestic release.
2. Tier-1 Importer-Distributors vs. Regional Sub-Distributors
Historically, international wineries assigned exclusive national distribution rights to single legacy trading houses in primary maritime gateways such as Shanghai, Guangzhou, Shenzhen, or Tianjin. Today, relying on a sole national distributor frequently leads to distributor inertia. The contemporary model splits wholesale rights into regional master distributors or engages tier-1 importers who operate dedicated sub-distributor networks across inland Tier-2 and Tier-3 commercial hubs.
3. Wholesale Margins and Working Capital
Each tier in mainland China extracts an operational margin:
- First-tier importers typically work on 20% to 35% gross margins, bearing clearance risk, port logistics, and bonded storage.
- Regional wholesalers and sub-distributors capture 15% to 25%, handling localized trucking, credit terms to restaurants, and regional promotions.
- Endpoints (retail/hospitality) apply 30% to 150% markups depending on the venue category.
Wineries must engineer flexible price ladders from Ex Works (EXW) through Free on Board (FOB) to ensure that the final shelf price in China remains commercially competitive after all intermediaries take their margin.
Physical Distribution Channels: Retail, Membership Clubs, and HoReCa
Once cleared through customs, wine enters distinct physical sales channels, each characterized by specific volume velocities, margin expectations, and purchasing criteria.
Modern Off-Trade and Membership Warehouse Clubs
Traditional hypermarkets have yielded ground to membership warehouse retailers. According to the USDA FAS Shanghai ATO 2025 Market Update, retail giants such as Sam’s Club and Costco China are actively leading the trend of self-sourcing wine selections, contributing substantially to commercial volume growth. These warehouse operators deal directly with brand owners or preferred primary importers, demanding high quality, recognized provenance, and aggressive volume pricing.
On-Trade (HoReCa) and Concept-Driven Venues
The on-premise sector is experiencing a structural pivot. While five-star hotels and banquet halls historically absorbed high volumes of corporate dining wines, modern consumption has migrated toward informal, lifestyle-oriented gastronomy. As highlighted by VVR International's 2026 market analysis, innovative and concept-driven bistros, natural wine bars, and regional Western-Asian fusion venues have emerged as vital distribution nodes for imported wines, particularly for white, sparkling, and lower-intervention varietals.
┌───────────────────────┬──────────────────────────┬────────────────────────────┐
│ Distribution Channel  │ Key Characteristics      │ Margin Profile / Dynamics  │
├───────────────────────┼──────────────────────────┼────────────────────────────┤
│ Membership Clubs      │ High volume, strict QA,  │ Low-to-moderate markups;   │
│ (Sam's Club, Costco)  │ direct/exclusive sourcing│ massive inventory movement │
├───────────────────────┼──────────────────────────┼────────────────────────────┤
│ Traditional HoReCa    │ Corporate banquets,      │ High markups (100–200%);   │
│ (Hotels, Fine Dining) │ established brand prestige│ slower turns, long credit  │
├───────────────────────┼──────────────────────────┼────────────────────────────┤
│ Concept Wine Bars &   │ Young demographic,       │ Healthy pour margins;      │
│ Modern Bistros        │ exploratory varietals    │ high educational appetite  │
├───────────────────────┼──────────────────────────┼────────────────────────────┤
│ Traditional E-Commerce│ Brand search, logistics, │ Highly transparent pricing;│
│ (Tmall, JD.com)       │ flagship stores          │ promotion-driven events    │
├───────────────────────┼──────────────────────────┼────────────────────────────┤
│ Social Commerce       │ Livestreaming, impulse,  │ High promotional spend;    │
│ (Douyin, Xiaohongshu) │ localized storytelling   │ strong brand discovery     │
└───────────────────────┴──────────────────────────┴────────────────────────────┘
The Digital Landscape: E-Commerce, Social Commerce, and Omnichannel
Digital channels in China do not merely act as transaction fulfillment centers; they serve as primary marketing engines and brand discovery platforms.
Traditional Marketplaces vs. Social Commerce
According to International Wine and Spirits Research (IWSR) data cited by China Briefing in October 2025, China's alcohol e-commerce market is projected to expand at a compound annual growth rate (CAGR) of 6% from 2022 to 2027, representing approximately 40% of the world's online alcohol sales. The digital architecture splits into two primary avenues:
- Search-Driven Marketplaces (Tmall, JD.com): Excellent for established brands where consumers actively search for specific SKUs. Official flagship stores establish brand authenticity and set the national price ceiling.
- Content- and Live-Driven Social Platforms (Douyin, Xiaohongshu/RED): These platforms leverage Key Opinion Leaders (KOLs) and short-form video to drive demand through localized cultural storytelling. Wineries that supply their distributors with localized creative assets achieve significantly higher conversion rates.
The Direct-to-Consumer (DTC) and Omnichannel Reality
True direct-to-consumer delivery from an overseas cellar to an individual Chinese home is structurally restricted by import duties, shipping latency, and regulatory barriers. Instead, successful brands build omnichannel models where digital channels generate brand visibility and consumer pull, while regional warehouse nodes and retail partners fulfill the product domestically within 24 to 48 hours.
Geographic Tiering: Navigating China’s Diverse Regional Markets
Treating China as a homogeneous marketplace is one of the most common pitfalls for international exporters. Consumption dynamics vary sharply across municipal classifications.
- Tier-1 Metropolises (Shanghai, Beijing, Guangzhou, Shenzhen): Home to highly sophisticated consumers, international sommelier communities, and established wine education networks. These markets exhibit high demand for diverse categories, including sparkling, organic, and boutique allocations.
- New Tier-1 and Provincial Capitals (Chengdu, Hangzhou, Wuhan, Xi'an): Rapidly expanding urban wealth coupled with vibrant dining cultures make these cities high-growth battlegrounds for foreign producers looking to expand beyond coastal markets.
- Tier-2 and Tier-3 Inland Cities: Dominated primarily by business gifting, weddings, and traditional banquets. Commercial success in these territories requires robust local distributor relationships with regional wholesale networks.
To identify commercial partners across these distinct economic zones, wine brands frequently analyze localized market insights and engage in pre-screened business matching before committing to territorial exclusivity.
Strategic Partner Selection: Avoiding Commercial Pitfalls
Expanding into China requires rigorous distributor evaluation. Exporters should vet potential commercial partners against four non-negotiable operational benchmarks:
- GACC Compliance and Active Import Licensing: Verify that the entity actively holds valid licenses and possesses operational experience managing CIFER filings, customs clearing, and Chinese back-label approvals.
- Cold-Chain Logistics Capabilities: Wine exposed to summer shipping conditions across southern Chinese ports will suffer irreversible heat damage. Importers must demonstrate temperature-controlled warehousing and refrigerated domestic transit contracts.
- Channel Specialization Alignment: A distributor whose primary revenue comes from industrial sales or corporate banquet contracts will rarely succeed with an artisanal biodynamic portfolio. Match your portfolio style to the distributor's core customer base.
- Commitment to Co-Investment and Brand Building: As observed in practical market analyses by the EU SME Centre, long-term brand success requires structured commercial collaboration—such as joint tasting allocations, education programs, and marketing budgets—rather than purely transactional container purchasing.
Action Plan: Establishing Your Route to Market with Interwine
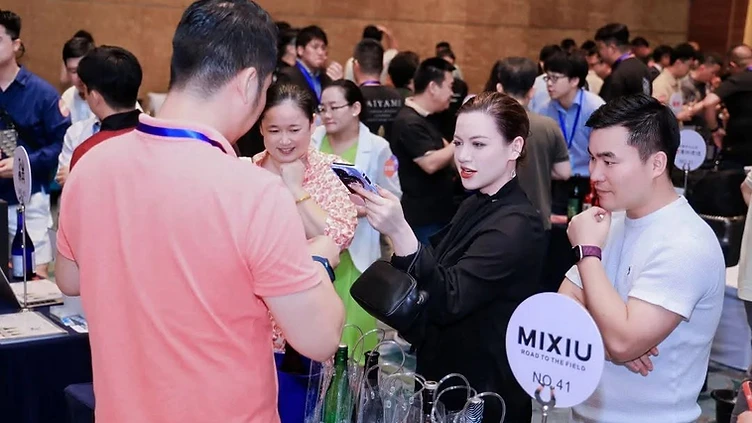
Navigating China’s multi-tiered distribution network requires qualified, face-to-face commercial dialogue with vetted importers, regional wholesalers, and retail buyers.
For winery export directors evaluating market entry or seeking to replace underperforming distribution partners, Interwine serves as mainland China's premier commercial gateway. By exhibiting at specialized trade events, producers meet verified importers, regional distributors, and purchasing heads across Tier-1, New Tier-1, and inland commercial clusters.
Take the definitive step to secure your brand's commercial route to market in mainland China. Review participation packages and register directly to become an exhibitor at Interwine's upcoming edition.
Sources
- USDA Foreign Agricultural Service (FAS) Shanghai ATO – Wine Market Update 2025 (Published September 23, 2025): https://apps.fas.usda.gov/newgainapi/api/Report/DownloadReportByFileName?fileName=Wine+Market+Update+2025_Shanghai+ATO_China+-+People%27s+Republic+of_CH2025-0190.pdf
- China Briefing / Dezan Shira & Associates – China's Wine Market Outlook: Trends and Opportunities (Published October 14, 2025): https://www.china-briefing.com/news/chinas-wine-market-outlook-trends-and-opportunities/
- VVR International – The Chinese Wine Market in 2026: Trends and Consumption (Published March 24, 2026): https://www.vvrinternational.com/en/the-chinese-wine-market-in-2026-trends-and-consumption/
- EU SME Centre – China's Wine Market Case Study Series: Exporting Wine, Forging Alliances, and Branding: https://www.eusmecentre.org.cn/publications/chinas-wine-market-case-study-series-michele-taccetti/
Key Takeaways
- —China imported roughly $1.6 billion in wine and related products in 2024 according to GACC/USDA FAS data, led by Australia and France.
- —A single national importer model is obsolete; effective market penetration requires regional master distributors or direct partnerships across Tier-1 and New Tier-1 hubs.
- —Membership clubs like Sam's Club and Costco are bypassing traditional wholesalers to self-source wine selections in high volumes.
- —China represents approximately 40% of global online alcohol sales, with IWSR forecasting a 6% e-commerce CAGR from 2022 to 2027.
- —Foreign wine producers must comply with GACC Decree 248/CIFER registration and domestic standard GB 15037 prior to shipping.
- —On-premise consumption is pivoting toward informal bistros, natural wine bars, and lifestyle venues, creating new demand for white and sparkling wines.
Frequently Asked Questions
Can an overseas winery sell directly to Chinese consumers or restaurants?
No. Under Chinese customs regulations, imported wine must be declared and cleared by a domestic enterprise possessing a valid food circulation permit and an import-export license. Overseas wineries must clear goods through a registered Chinese importer before distribution to restaurants, retailers, or end consumers.
What regulatory filings are required before shipping wine to China?
Wineries must be registered in the China Import Food Enterprise Registration (CIFER) system managed by the General Administration of Customs China (GACC) under Decree 248. Products must also comply with national food safety standards, including GB 15037 for wine and GB 7718 for compliant Chinese back labels.
How do wholesale and distribution margins function across China?
First-tier importers typically operate on 20% to 35% gross margins to cover clearance, customs handling, and bonded storage. Regional sub-distributors add 15% to 25% for localized delivery and credit terms, while retail and on-premise venues apply 30% to 150% markups depending on venue positioning.
Why are membership warehouse clubs gaining importance in wine distribution?
Retailers such as Sam's Club and Costco have expanded rapidly across Chinese Tier-1 and New Tier-1 cities. By self-sourcing wines directly from producers or tier-1 importers, they provide brand visibility and rapid turnover for wines that meet their stringent quality and pricing specifications.
How should an export director choose between exclusive and regional distributors?
Given China's vast geographic scale, granting national exclusivity to a single partner carries the risk of underperformance in secondary markets. Many brands prefer appointing regional distributors (e.g., East China, South China, Northern/Inland hubs) or partnering with a nationwide importer that provides contractual sales performance minimums per province.