Offline Wine Sales Channels in China
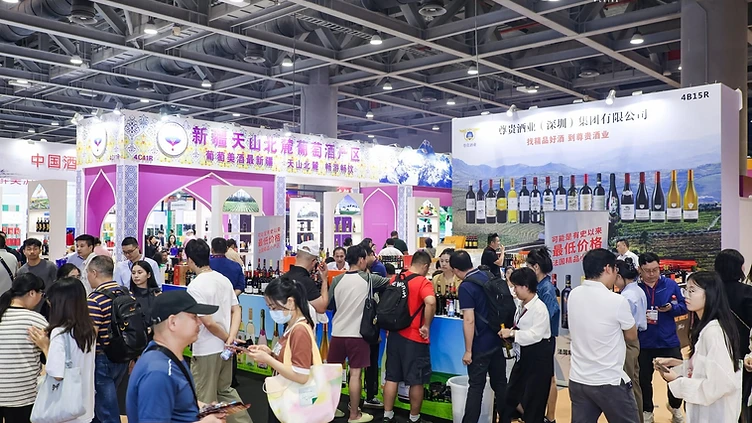
A commercial B2B guide exploring offline wine sales channels in China, evaluating modern supermarkets, duty-free hubs, specialty bottle shops, HoReCa, and regional distribution routes.
Despite China's status as a global pioneer in digital commerce, physical distribution remains the indispensable bedrock for building brand value, protecting price architecture, and securing commercial scale. For international wineries entering or expanding across mainland China, offline retail and on-premise channels provide sensory trial, verified provenance, and direct touchpoints for high-value business gifting and corporate entertainment.
According to an analysis presented by Metro China at ProWine Shanghai (citing IWSR data), wine sales through off-premise retail channels rose from 46.8% in 2022 to 66.3% in 2023, while e-commerce represented 23.9% of that retail segment. Physical stores, specialty boutiques, hospitality venues, and wholesale networks continue to control the majority of volume and premium margin. Navigating these offline channels requires foreign producers to assess channel-specific margins, geographic purchasing behaviors, and the compliance requirements of General Trade clearance.
Structure of China's Offline Retail Landscape
Offline wine retailing in China is segmented across several retail formats, each catering to distinct consumer intents, price points, and stocking models. Understanding how volume and revenue divide across physical formats allows wineries to allocate inventory rationally.
+-------------------------------------------------------------+
|         OFFLINE WINE RETAIL FORMAT BREAKDOWN (2024)         |
+-----------------------------------+-------------------------+
| Format                            | Market Share Percentage |
+-----------------------------------+-------------------------+
| Supermarkets & Hypermarkets       | 37%                     |
| Convenience Stores (C-Stores)     | 16%                     |
| Specialty Beverage & Wine Shops   | 15%                     |
| Duty-Free Shops                   | 14%                     |
| Discount & Outlet Retailers       | 8%                      |
| Other Formats                     | 10%                     |
+-----------------------------------+-------------------------+
(Source: Statista 2024 data presented by Metro China category leadership at ProWine Shanghai).
1. Modern Supermarkets, Hypermarkets, and Membership Clubs
Supermarkets and hypermarkets account for roughly 37% of China's offline wine sales. High-volume multinational and regional chains—such as Metro China, Sam’s Club (Walmart), RT-Mart, and CR Vanguard (Olé)—form the primary buying ground for middle-class daily consumption and festive gifting.
Metro China operates approximately 100 stores across 60 Chinese cities with over 3 million members. According to retail performance data shared by Vino Joy News (2024), 70% of Metro’s RMB 600 million annual wine sales occur directly inside physical stores, with 50% to 60% of their 500-label inventory positioned in the premium bracket of RMB 200 to 300 per bottle. Big-box membership warehouse clubs demand strictly controlled pricing, dependable stock volume, and presentation packaging (such as seasonal gift twin-packs), while boutique modern grocers like Olé favor organic, biodynamic, and recognizable Old World AOC designations.
2. Specialty Independent Bottle Shops and Fine Wine Boutiques
Accounting for 15% of offline retail volume, specialty wine stores are the primary vehicle for high-end boutique estates, allocation-only crus, and niche varietals. Concentrated in Tier-1 and dynamic New Tier-1 urban centers (Shanghai, Beijing, Shenzhen, Guangzhou, Chengdu, and Hangzhou), these shops cater to educated enthusiasts, corporate procurement managers, and private collectors.
Unlike hypermarkets, specialty merchants prioritize producer heritage, provenance, and sommelier curation over high listing allowances. However, order volumes per store remain comparatively modest. Successful boutique placement serves as a credibility anchor, supporting brand equity that trickles down into wholesale and regional trade.
3. Convenience Stores (C-Stores)
Convenience chains—such as FamilyMart, 7-Eleven, Lawson, and local regional banners—account for 16% of offline retail sales. C-stores serve immediate, spontaneous consumption among younger white-collar urbanites. Stocking parameters in this channel are rigid: space is constrained, inventory turns must be rapid, and shelf pricing concentrates below RMB 100 per 750ml bottle, with increasing rotation of half-bottles (375ml) and single-serve formats.
4. Travel Retail and Duty-Free Outlets
Holding 14% of the offline market, travel retail has expanded following offshore duty-free policies in Hainan Province. High-end estates leverage airport duty-free corridors and downtown bonded retail emporiums to reach domestic luxury travelers who purchase status-aligned single bottles and wooden collector sets for business gifting.
On-Premise and HoReCa Dynamics
The Chinese Food Service and hospitality sector represents a vital channel for consumer trial, brand storytelling, and high-margin realization, as highlighted in reports on domestic distribution channels by Market Research Future (2026).
Luxury Hotels and Western Dining
Five-star international hotel groups (Marriott, Hyatt, Accor) and Western fine dining restaurants in coastal metros manage curated wine programs driven by certified sommeliers. These venues establish prestige for premium labels. However, wineries must navigate distributor listing fees (kaidianfei), long payment terms (often 60 to 90 days), and demand for comprehensive staff tasting training.
Chinese Banqueting and High-End Dining (Baojian)
Mainland China’s domestic business banquet segment remains heavily centered on private dining rooms (baojian). Historically dominated by domestic Baijiu, banquets frequently incorporate prestigious imported red wines to symbolize status, hospitality, and respect (mianzi). Strong, structured reds (such as Bordeaux blends, Barossa Shiraz, and Napa Cabernet) dominate this space. Channel entry depends heavily on sub-distributors who maintain proprietary corporate and regional commercial networks.
Casual Bistros and Hybrid Wine Bars
A prominent development across Shanghai, Chengdu, and Shenzhen is the proliferation of natural wine bars, French-style bistros, and daytime café/evening wine bar hybrids. These venues bypass rigid corporate structures, welcoming progressive natural, low-intervention, orange, and cool-climate white wines. Margins are competitive, and rotations are driven by younger consumer discovery.
Channel Comparison: Commercial Viability Matrix
+---------------------+-------------------+---------------------+--------------------+
| Offline Channel     | Average Price/Btl | Primary Driver      | Barrier to Entry   |
+---------------------+-------------------+---------------------+--------------------+
| Hypermarkets/Clubs  | RMB 120 - 300     | Volume, Gifting     | Listing fees, Scale|
| Specialty Stores    | RMB 250 - 1,500+  | Curation, Heritage  | Sommelier buy-in   |
| Convenience Stores  | RMB 40 - 100      | Instant Consumption | Slotting costs     |
| Fine Dining/Hotels  | RMB 350 - 2,000+  | Status, Gastronomy  | Payment credit terms
| Casual Wine Bars    | RMB 180 - 450     | Social Discovery    | Constant rotation  |
+---------------------+-------------------+---------------------+--------------------+
Regional Offline Distribution Architecture: Beyond Tier-1
Winning offline distribution across China requires looking past coastal Tier-1 hubs. While Shanghai and Guangzhou remain operational import and trendsetting gateways, interior New Tier-1 and Tier-2 metropolitan zones represent growing volume opportunities:
- The Greater Bay Area (Guangdong-Hong Kong-Macao): China's commercial engine for imported wine consumption. Distribution here is mature, commercially savvy, and deeply rooted in Cantonese business dining traditions.
- Eastern Commercial Corridor (Jiangsu, Zhejiang, Shanghai): Highest density of specialty wine shops, bistro culture, and high-spending retail membership club footfall.
- Southwestern Hubs (Chengdu, Chongqing): Leading lifestyle markets exhibiting surging leisure spending, burgeoning bistro networks, and rising consumption of crisp whites and lighter reds.
- Northern Metros (Beijing, Tianjin, Shandong): Structured, formal corporate entertainment environments favoring institutional gifting, full-bodied reds, and prestigious packaging.
Foreign producers cannot service regional sub-distributors directly from abroad. General Trade operations necessitate an established network of regional wholesalers (Yiji/Erji dailishang) who purchase stock from national importers to place in regional supermarket branches, local retail shops, and independent restaurants.
For real-time commercial guidance on navigating these tiers, explore our curated Market Insights and current coverage in our industry News and Magazine.
Regulatory and Compliance Prerequisites for Offline Channels
Unlike Cross-Border E-Commerce (CBEC), selling through physical retail and hospitality venues in mainland China requires full General Trade customs clearance, as outlined in detailed operational guidance from the EU SME Centre (2023):
- GACC Manufacturer Registration: Every foreign winery must secure an active registration number through the General Administration of Customs of China (GACC) CIFER platform prior to dispatch. This 18-digit code must appear on outer shipping cartons and documentation.
- Chinese Back-Label Compliance: Physical retail products must bear a compliant Chinese back-label before customs clearance. Key declarations include exact legal product designations, net content, alcohol percentage, importer/distributor contact information, and mandatory ingredient statements (such as sulfur dioxide declarations).
- Sanitary Inspection & Certificate of Quality: Shipments undergo sampling analysis for heavy metals, chemical additives, and microbiological thresholds. Goods can only enter domestic warehouses and physical distribution routes after the Customs Inspection and Quarantine (CIQ) certificate is released.
Overcoming Offline Channel Expansion Challenges
Expanding into China’s physical channels carries commercial hurdles that require clear proactive policies:
- Channel Conflict and Price Undercutting: A recurring failure mode occurs when e-commerce discount discounters undercut offline retail shelf pricing. Traditional physical retailers and hospitality managers will de-list labels if their operating margins (typically 30% to 50%) are compromised by online grey-market pricing.
- Payment Terms and Working Capital Pressure: Major supermarket operators and hotel chains frequently demand 60-to-120-day credit terms, listing fees (kaidianfei), and promotional subsidies. International producers must partner with well-capitalized first-tier importers capable of carrying these terms.
- Building In-Market Relationship Capital (Guanxi): Business relationships across Chinese regional distribution networks remain personal. Importers, master distributors, and channel buyers commit to long-term inventory investments only after meeting foreign winery principals face-to-face and sampling the wines together.
To bridge the gap between global cellars and qualified regional buyers, wineries utilize structured commercial programs. Wineries can tap into targeted distribution networks by securing direct meetings with verified buyers through our tailored Business Matching services, or establish a dedicated regional market presence by choosing to Become an Exhibitor at upcoming trade showcases.
Sources
- Vino Joy News (2024) - Industry analysis covering Metro China wine sales, off-premise channel distribution figures, and Statista retail data presented at ProWine Shanghai.
- EU SME Centre (2023) - Market overview outlining China's wine market regulatory procedures, GACC CIFER compliance, customs clearance, and distribution channels.
- USDA Foreign Agricultural Service (2025) - Wine Market Update China report covering importer distributions, regional channels, and hospitality sector structures.
- Market Research Future (2026) - Comprehensive industry forecast examining wine packaging dynamics, on-premise food service, and retail distribution trends across China.
Key Takeaways
- —Off-premise retail channels captured 66.3% of China's wine sales volume according to 2023 IWSR data, demonstrating the continued supremacy of physical retail over digital-only routes.
- —Supermarkets, hypermarkets, and warehouse clubs represent the largest offline retail share at 37%, followed by convenience stores (16%) and specialty wine shops (15%).
- —Metro China generates 70% of its RMB 600 million annual wine sales via physical brick-and-mortar stores, highlighting strong demand for mid-to-premium bottles priced between RMB 200 and 300.
- —General Trade clearance—including mandatory GACC CIFER registration and compliant Chinese back-labeling—is required for all physical retail and HoReCa distribution in China.
- —Preserving offline distributor and retailer margins requires strict control over e-commerce discounting to prevent destructive cross-channel price cannibalization.
Frequently Asked Questions
What is the largest offline sales channel for wine in mainland China?
According to Statista and Metro China retail data, supermarkets, hypermarkets, and big-box club stores lead the offline retail sector, accounting for approximately 37% of sales, followed by convenience store chains at 16% and specialty beverage stores at 15%.
Why do physical wine sales remain so high compared to China's booming e-commerce?
Physical channels provide verifiable product provenance, immediate temperature-controlled fulfillment, personalized sommelier advice, and direct suitability for spontaneous corporate dining and luxury gift-giving, where packaging condition and anti-counterfeiting assurance are critical.
What regulatory approvals are needed to sell wine in physical Chinese stores?
Wines sold in offline retail and on-premise venues must enter via General Trade. This requires the overseas production facility to be registered with China's GACC CIFER system, products to bear fully compliant Chinese back-labels, and shipments to pass customs sampling tests to obtain a CIQ inspection certificate.
How do international wineries prevent online discounts from destroying offline retail relationships?
Brands must establish strict Minimum Advertised Price (MAP) policies, monitor major digital platforms, and differentiate SKUs by reserving specific labels, formats, or gift packaging exclusively for offline physical retailers and HoReCa venues.
What typical retail price point moves fastest in Chinese modern supermarket chains?
In premium supermarket and warehouse club channels like Metro China, commercial velocity centers heavily in the RMB 120 to RMB 300 bracket, with 50% to 60% of top-performing selections priced between RMB 200 and RMB 300.