Fine Wine Distribution Opportunities in the Chinese Market
Discover current fine wine distribution opportunities in the Chinese market. Explore channel structures, evolving consumer demographics, tariff developments, and B2B partner selection strategies.
China's fine wine sector is undergoing a profound structural evolution. For international wine estates, boutique cellars, and brand owners evaluating fine wine distribution opportunities in the Chinese market, the era of unguided speculation and broad, passive import contracts is gone. Success today requires targeted distribution strategies, an intimate grasp of localized retail dynamics, and direct engagement with regional channel partners.
According to an industry valuation report by Market Research Future, China's domestic wine market reached $18.85 billion in 2024 and is projected to expand to $20.25 billion in 2025, charting a path toward $41.25 billion by 2035 with a compound annual growth rate (CAGR) of 7.38%. While mass-market bulk volumes have faced headwinds, premium and fine wine segments remain resilient. Driven by middle-class and affluent consumers seeking provenance, artisanal authenticity, and personal enjoyment, wine importers and distributors are recalibrating their portfolios to focus on higher margin, prestige products.
To capture market share in this transitioning landscape, global wineries must decode China’s distribution infrastructure, regional sales mechanics, and key regulatory requirements.
Shifting Dynamics in China's Fine Wine Trade
Historically, fine wine across Mainland China was driven predominantly by high-end banqueting, state-level gifting, and corporate hospitality. However, structural shifts and evolving consumption habits have redefined the primary drivers of demand. As detailed in the Journal of Wine Economics (2025), commercial buying patterns have moved firmly toward self-consumption, casual social gatherings among younger professionals, and specialized collector communities.
International trade frameworks have also shifted. In March 2024, China's Ministry of Commerce officially lifted punitive anti-dumping tariffs on Australian bottled wine exports, ending a three-year freeze and rapidly restoring historical supply links, as tracked by MS Advisory. Leading global brand holders moved swiftly to re-establish logistics; for instance, Australian family-owned producer De Bortoli Wines finalized a distribution agreement with nationwide importer ASC Fine Wines in June 2024, as reported by The Drinks Business.
Concurrently, China officially joined the International Organisation of Vine and Wine (OIV) as its 51st member state in late 2024 with formal ratification rolling out through 2025, noted by Jane Anson. This milestone signals deeper technical integration, harmonized testing protocols, and standard-aligned trade relations with major winemaking nations.
Core Distribution Channels for Fine Wine
Academic analysis published on ResearchGate examining comparative wine distribution systems highlights that while mature Western markets lean heavily on off-trade hard discounters, China’s market has historically centered on high-touch on-trade channels, specialized wine retail, and regional wholesaler tiers. Today, distribution routes are fragmenting into distinct high-performing avenues:
1. Prestige On-Trade and Specialist Hospitality
Fine dining establishments, luxury hotel dining rooms, Western-style bistro bars, and private clubs in Tier-1 metropolises (Shanghai, Beijing, Shenzhen, Guangzhou) serve as frontline tasting grounds. Sommelier endorsements, wine-by-the-glass initiatives, and seasonal wine-pairing menus remain essential for establishing brand prestige and generating immediate word-of-mouth visibility.
2. Tier-2 and Tier-3 City Regional Distributors
While Tier-1 cities are hyper-competitive, substantial margin opportunities reside in affluent secondary hubs such as Chengdu, Hangzhou, Wuhan, and Qingdao. Regional sub-distributors in these economic centers often possess direct networks among local entrepreneurs, corporate accounts, and private cellars that national tier-one trading houses cannot penetrate with equal intimacy.
3. Boutique Fine Wine Retailers and Private Client Direct Networks
Independent wine boutiques, high-end member cellars, and regional tasting lounges function as curated gatekeepers. They organize structured masterclasses, bespoke tastings, and en primeur campaigns for private collectors, offering producers an environment where story, terroir, and critical acclaim command full retail margin.
4. Cross-Border and Closed-Loop Digital Channels
While general consumer goods depend on broad e-commerce giants, fine wine thrives on private social commerce (WeChat mini-programs) and specialized content-driven channels. These platforms minimize intermediary pricing distortion, facilitate authentic storytelling through video masterclasses, and provide secure cold-chain delivery directly to discerning consumers.
Structural Barriers, Risks, and Margin Management
Navigating China’s distribution sector requires proactive planning around financial, logistical, and legal considerations:
- Multi-Tiered Markups and Channel Margin Erosion: Fine wine passing through an importer, master distributor, regional sub-wholesaler, and final venue faces sequential markups that can price imported labels out of retail competitiveness. Wineries must maintain strict Recommended Retail Price (RRP) discipline and work with partners capable of direct-to-retail or single-tier fulfillment.
- Cold-Chain Logistics Integrity: Temperature spikes across southern ports or continental interiors pose acute risks to unpasteurized, low-sulfur, or fine vintage bottles. Retaining verified refrigerated containers (reefer containers) and temperature-controlled domestic warehousing is non-negotiable.
- Customs Compliance and Labeling: Standard customs duty rates apply based on bilateral free trade agreements or Most Favored Nation (MFN) tariff schedules (ranging between 14% to 30% for non-treaty nations), combined with Value-Added Tax (13%) and statutory Consumption Tax (10%). Chinese back-labels must strictly conform to State Administration for Market Regulation (SAMR) guidelines regarding allergen disclosures, geographical designations, and authorized importer information.
- Brand Squatting and Intellectual Property: Foreign trade names and phonetically transliterated Chinese characters must be registered with the China National Intellectual Property Administration (CNIPA) prior to product dispatch. Failure to protect trademark derivatives allows unauthorized entities to register local brand equivalents, halting legitimate customs clearance.
To stay informed about legislative developments, customs updates, and industry logistics, review regular updates in Market Insights and News and Magazine.
Strategic Recommendations for Brand Owners
For category producers seeking sustained distribution footprints, a systematic entry or expansion playbook is critical:
[Phase 1: Compliance & Trademark Registration]
                 ↓
[Phase 2: Segment Portfolio & Identify Niche Positioning]
                 ↓
[Phase 3: Direct Engagement via In-Person Trade Fairs]
                 ↓
[Phase 4: Structured Due Diligence & Commercial Contracting]
                 ↓
[Phase 5: Collaborative Marketing, Sampling, & Education]
- Curate Portfolio Portions Strategically: Do not push entry-level labels under the guise of prestige. Chinese sommeliers and merchant buyers are knowledgeable, holding certifications from WSET and Court of Master Sommeliers. Allocate single-vineyard expressions, limited library releases, or organic/biodynamic selections that present a clear, authentic identity.
- Avoid Absolute National Exclusivity: Handing exclusive national distribution rights to a single importer can backfire if their regional reach outside Tier-1 cities is weak. Consider assigning rights by trade channel (e.g., specialized on-premise vs. private client channels) or geographical zones (e.g., East China, South China, Southwest).
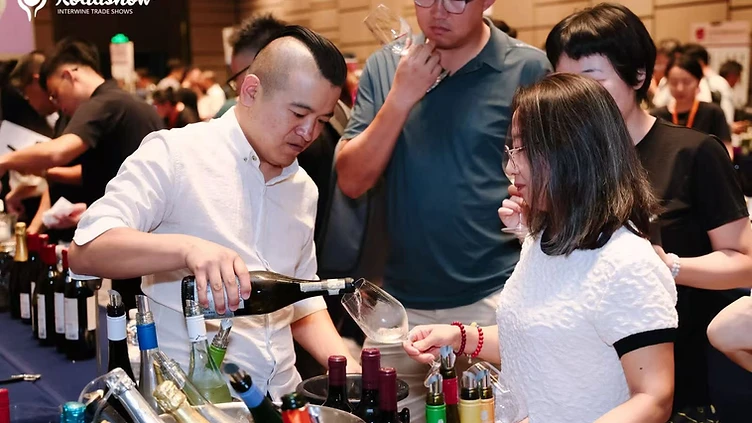
- Engage Directly in Face-to-Face Trade Exhibitions: Importers, provincial buyers, and restaurant group directors rarely commit to overseas accounts purely via digital correspondence. Physical sampling, mutual vetting, and in-person relationship building remain irreplaceable.
Producers seeking verified regional distributor connections can optimize their commercial outreach by exploring options to Become an Exhibitor at upcoming trade events. Participating brands can coordinate targeted trade meetings using specialized Business Matching services, engage with prospective peers via the Exhibitor Directory, and plan their travel logistics efficiently through Hotel Accommodation support.
Conclusion
The Chinese fine wine sector has transformed into a discerning, quality-driven marketplace. As China's total market value advances toward the $20 billion threshold in 2025 and pursues sustained long-term growth, international wineries equipped with clear brand positioning, robust legal safeguards, and reliable regional distributor networks are positioned to capture meaningful market share. Direct relationship-building with qualified importers remains the most dependable path to long-term commercial success.
Sources
- Market Research Future: China Wine Market Size, Share Industry Analysis By 2035
- Cambridge University Press: China’s wine market: Recent shocks, long-term prospects - Journal of Wine Economics
- MS Advisory: Wine Market in China: Trends, Growth, and Consumer Behavior
- The Drinks Business: ASC scores distribution deal with De Bortoli in China
- ResearchGate: Wine distribution channel systems in mature and newly growing markets: Germany versus China
Key Takeaways
- —Market Research Future projects the China wine market to grow from $18.85B in 2024 to $20.25B in 2025, reaching $41.25B by 2035 at a 7.38% CAGR.
- —China's removal of punitive tariffs on Australian wine in March 2024 and accession to the OIV in late 2024 mark a more standardized, internationally integrated regulatory era.
- —Fine wine consumption has pivoted from ceremonial gifting and state-backed banquets to personal appreciation, casual social gatherings, and specialist collector acquisitions.
- —High-margin distribution opportunities are shifting beyond saturated Tier-1 centers toward affluent Tier-2 and Tier-3 urban markets such as Chengdu, Hangzhou, and Wuhan.
- —Securing Chinese trademark rights with CNIPA and establishing end-to-end temperature-controlled supply chains are foundational requirements before signing distribution agreements.
- —Direct, face-to-face commercial networking at trade exhibitions remains the industry benchmark for securing reputable, active distribution partners across Mainland China.
Frequently Asked Questions
What is the projected value of China's wine market in 2025?
According to Market Research Future (2024), the Chinese wine market was valued at $18.85 billion in 2024 and is projected to expand to $20.25 billion in 2025, exhibiting a long-term CAGR of 7.38% through 2035.
How did the 2024 tariff lift impact wine imports into China?
In March 2024, China officially rescinded punitive import duties on Australian wine, opening the market for key international estates to re-establish national distribution agreements and reinvigorate competitive trade dynamics across major importers.
Which channels drive the highest sales for imported fine wine in China?
Premium on-trade venues (hotels, Michelin/Black Pearl restaurants, independent bistros), boutique specialty bottle shops, private collector clubs, and curated WeChat social-commerce channels generate the strongest margins for imported fine wine.
Should foreign wineries grant national exclusivity to a single Chinese distributor?
Generally, no. Unless a distributor has proven nationwide operational coverage across both on-trade and off-trade networks, brands benefit more by splitting exclusive rights by region (e.g., East China vs. South China) or trade channel to prevent underperformance.
What IP protections are needed before shipping wine to China?
Brands must register both their Latin brand name and a curated Chinese phonetic trademark with the China National Intellectual Property Administration (CNIPA) under the 'first-to-file' system prior to product dispatch to prevent trademark hijacking.