Choosing a Route to Market for Wine in China
Choosing the right route to market for wine in China requires navigating evolving distribution channels, direct-to-retail trends, regulatory compliance, and targeted buyer matching across tier-one and emerging regional hubs.
Choosing an effective route to market for wine in China is no longer a matter of simply signing an exclusive agreement with a national distributor and waiting for reorders. The mainland Chinese wine market has matured into a regionally segmented, commercially sophisticated landscape where route-to-market decisions directly dictate margin retention, inventory turnover, brand equity, and regulatory exposure.
According to the USDA Foreign Agricultural Service (FAS) Shanghai Wine Market Update (2025), China imported approximately $1.6 billion worth of wine and related products in 2024, with Australia and France commanding the leading market shares. Following China’s official lifting of anti-dumping and countervailing duties on Australian bottled wine in March 2024, Australian imports surged past 500 million Australian dollars that same year, reshaping supply-chain dynamics and intensifying shelf-space competition across national retail networks, as highlighted by Jane Anson's 2025 Market Insights. Wineries entering or restructuring their presence must evaluate route architectures against concrete criteria: working capital limitations, brand positioning, category consumption shifts, and localized compliance mandates.
Core Distribution Models: Structural Pros, Cons, and Commercial Realities
Foreign wine producers generally operate through four primary routes to market in China, each carrying distinct capital requirements, channel control dynamics, and operational trade-offs.
Foreign Winery
 │
 ├──> Tier-1 Master Importer ───────> Regional Sub-Distributors ──> Retail/On-Trade
 │
 ├──> Regional Importers/Wholesalers ─────────────────────────────> Local On-Trade / Specialized Retail
 │
 ├──> Direct-to-Enterprise Retail (Sam's Club, Costco, Hema) ──────> End Consumer
 │
 └──> Cross-Border E-Commerce (CBEC) / Social Commerce ───────────> Direct-to-Consumer (DTC)
1. The National Master Importer Model
Under this traditional structure, an exporter assigns nationwide distribution rights to a single major trading house or importer. The master importer takes title at the port of departure (FOB) or port of entry (CIF), handles customs clearance via the General Administration of Customs of the People's Republic of China (GACC), and distributes downward through secondary and tertiary regional wholesalers.
- Advantages: Minimal administrative overhead for the winery; simplified invoicing; high initial container volume commitments.
- Disadvantages: Severe loss of commercial visibility and brand control. Master importers often demand steep marketing subsidies and may deprioritize boutique SKUs in favor of high-turnover volume brands. If market demand cools, inventory accumulates in non-transparent provincial warehouses.
2. Regional and City-Tiered Direct Wholesalers
Rather than relying on a single national partner, wineries allocate import agreements based on geographical tiers—such as East China (Shanghai, Jiangsu, Zhejiang), South China (Guangdong, Shenzhen), North China (Beijing, Tianjin), and West China (Chengdu, Chongqing). As noted in academic research on international wine channel choices published on ResearchGate, Chinese wine market players place pronounced weight on commercial turnover and localized on-trade channels compared to mature European discount-led structures.
- Advantages: Closer access to end accounts; localized inventory placement; tailored promotional campaigns matching local dining cultures.
- Disadvantages: Wineries must manage multiple contracts, monitor parallel imports between provinces, and handle fractured logistics.
3. Direct-to-Enterprise Retail (Club Stores and Modern Off-Trade)
Membership club formats and premium grocery chains have emerged as dominant direct wine buyers. The USDA FAS 2025 Wine Market Update notes that retail giants including Sam’s Club, Costco China, Hema Fresh, and Ole' are increasingly self-sourcing wines directly from producers to bypass multi-layered distributor margins.
- Advantages: Immediate access to millions of upper-middle-class urban consumers; high-volume procurement; rapid cash cycles.
- Disadvantages: Stringent pricing pressure, demanding private-label tenders, and substantial listing and delivery performance penalties.
4. Cross-Border E-Commerce (CBEC) and Social Commerce DTC
Cross-border bonded warehouses in pilot free-trade zones allow producers to sell directly to Chinese consumers via platforms such as Tmall Global, JD Worldwide, and Douyin without prior traditional Chinese back-label printing. Furthermore, localized live-commerce and content curation on platforms like Xiaohongshu (RED) have become critical for consumer acquisition.
- Advantages: Preserves pricing autonomy; bypasses certain domestic market-entry registration bottlenecks; enables agile consumer testing for niche varieties.
- Disadvantages: Substantial platform fees, high customer acquisition costs (CAC), and severe dependency on algorithm-driven influencer (KOL) livestreams.
Evaluating Channel Fit: Price Tiers, Regions, and Consumer Trends
Selecting a route requires aligning your product portfolio with current shifts in Chinese consumer demographics and regional consumption patterns.
| Price Tier / Wine Style | Ideal Primary Route | Secondary Channel | Key Channel Requirement | | :--- | :--- | :--- | :--- | | Entry-to-Mid (Below $15 retail) | Direct Club Retail / Mass Modern Trade | High-Volume Regional Distributors | Scalable supply, aggressive pricing, GACC compliance | | Mid-to-Premium ($15–$50 retail) | Multi-Regional Importers / Fine Wine Wholesalers | Boutique E-Commerce & On-Trade | Storytelling, localized food-pairing, regional tastings | | Ultra-Premium / Icon ($50+ retail) | Specialist Allocators / Luxury Hospitality On-Trade | Private Client Direct / Cross-Border DTC | Brand pedigree, provenance tracking, masterclasses | | White, Rosé & Sparkling Wines | Tier-1 Metro Specialist Distributors (East/South) | Social Commerce / Modern Bistro On-Trade | Fast cold-chain, lifestyle marketing, social media presence |
Regional dynamics play a significant role. First-tier hubs like Shanghai, Shenzhen, Guangzhou, and Chengdu possess mature wine-drinking populations displaying expanding appetites for sparkling wines, aromatic whites, and natural or organic expressions, according to the USDA FAS 2025 Report. Conversely, northern and inland interior markets remain predominantly red-wine-centric, reliant on traditional corporate gifting and banquet distribution channels.
Regulatory and Operational Prerequisites
Before executing any route-to-market contract, overseas wineries must establish strict operational compliance to avoid customs seizures or costly delays at domestic ports:
- GACC Manufacturer Registration (Decree 248): All overseas production, processing, and storage facilities for imported food and beverages must register through China's CIFER portal, as detailed in export guidelines from the EU SME Centre (2024). Shipments without valid GACC registration numbers displayed on the shipping documentation and packaging will be denied customs entry.
- National Standards (GB Code) Labeling Compliance: Back labels must strictly comply with GB 7718 (General Standard for the Labeling of Prepackaged Foods) and GB 2758 (National Food Safety Standard for Fermented Alcoholic Beverages). Mandatory details include legal product name, ingredients (including added sulfites), alcohol percentage, country of origin, net content, storage instructions, bottling date, and Chinese domestic distributor credentials.
- Trademark Protection: China operates on a strict "first-to-file" intellectual property regime. Exporters must secure Chinese character trademarks alongside Roman-alphabet brand names with the China National Intellectual Property Administration (CNIPA) well before entering commercial discussions to prevent opportunistic trademark squatting.
Overcoming Intermediary Friction Through Direct Trade Matching
One of the most persistent failure modes for international wineries in China is contracting with regional "box-movers" who lack genuine distribution networks in target retail and dining segments. Traditional broker arrangements often insert unnecessary margin markups, leaving products uncompetitive against local and tariff-advantaged imports.
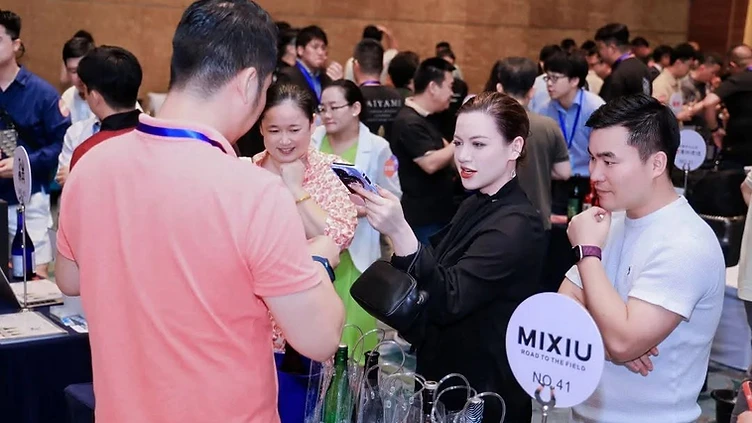
To establish long-term route sustainability, overseas producers are shifting toward targeted, qualified commercial encounters. Engaging in curated Business Matching enables producers to meet pre-vetted regional distributors, retail procurement managers, and specialized on-trade sommeliers who match the winery’s specific regional focus and price segment. Combining targeted B2B meetings with direct exhibition participation at physical trade gateways—supported by detailed Market Insights—allows producers to audit buyer distribution capacity, review competitor shelf positioning, and structure contracts with clear minimum performance clauses.
Wineries planning on-site market verification can streamline operational preparations through dedicated trade resources for Arrival and Transportation to optimize itineraries across core commercial clusters.
Strategic Conclusion and Next Steps
Choosing a route to market for wine in China demands a balanced commercial architecture. Producers must avoid over-relying on single national master distributors, align their pricing and varietals with regional consumption differences, secure GACC and trademark registrations early, and engage directly with verified regional procurement partners.
To de-risk your commercial expansion and connect with screened Chinese importers, buyers, and channel specialists, schedule targeted meetings through the dedicated Business Matching program at INTERWINE.
Sources
- USDA Foreign Agricultural Service (FAS) Shanghai - Wine Market Update 2025
- Jane Anson - Market Insights: Chinese Wine Industry in 2025
- EU SME Centre - How Can I Export Wine to China? Regulatory Guidelines (2024)
- ResearchGate - Wine Distribution Channel Systems: Germany Versus China (2026 Analysis)
Key Takeaways
- —China imported approximately $1.6 billion in wine in 2024, led by Australia and France, with Australian shipments expanding dramatically after tariffs were lifted in March 2024.
- —Relying on a single exclusive national distributor often obscures market visibility, prompting brands to favor regionalized distributor networks or direct club retail models.
- —Major retail chains such as Sam's Club, Costco, and Hema are driving direct self-sourcing partnerships, bypassing traditional multi-tier distributor markups.
- —Compliance requires mandatory CIFER manufacturer registration under GACC Decree 248, strict GB label translation, and early first-to-file trademark filings.
- —Pre-screened business matching and direct B2B buyer introductions are critical to vetting genuine regional distribution power and avoiding non-performing intermediaries.
Frequently Asked Questions
What is the most effective distribution model for an entry-to-mid tier wine brand entering China?
For entry-to-mid tier brands ($10–$25 retail), multi-regional distribution combined with direct relationships with large retail chains (such as Sam's Club, Costco China, or Hema) provides the best balance between volume and margin. Sole national distributors often fail to provide dedicated focus for mid-tier labels.
What mandatory certifications must wineries obtain before exporting to mainland China?
Overseas wineries must complete enterprise registration through the GACC CIFER platform in accordance with Decree 248, obtain compliant Chinese back labels adhering to GB 7718 and GB 2758 standards, and register trademark rights under China's first-to-file system to prevent IP theft.
How did the removal of Australian wine tariffs in 2024 alter distribution channels?
The lifting of anti-dumping duties in March 2024 triggered over AU$500 million in Australian wine imports that year, intensifying competition for shelf space and prompting distributors across tier-one and tier-two cities to re-evaluate their international supplier portfolios.
Why are membership club stores becoming key direct wine buyers in China?
Retailers such as Sam's Club and Costco China increasingly source directly from producers to remove intermediary distributor markups, pass cost savings to their middle-class members, and guarantee authenticity and product consistency.
How can wineries vet prospective Chinese distributors before signing commercial agreements?
Wineries should conduct physical due diligence, check importer credit and customs records, require transparent distribution channel breakdowns by province, and use structured B2B business matching programs at industry trade fairs to interface with verified buyers.